Robinhood Banking
Robinhood
- 4.9
- 1.54K Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
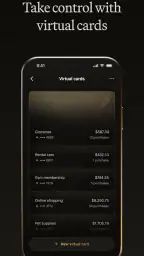
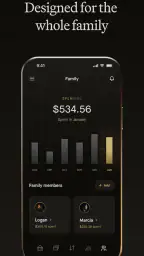
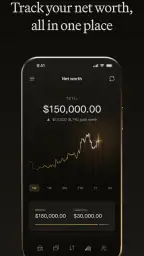
Robinhood Banking Pros and Cons
Pros
- User-friendly interface for beginners.
- Commission-free trades save money.
- Real-time market data access.
- Easy account setup process.
- Diverse investment options available.
Cons
- Limited customer support options.
- No retirement accounts available.
- Cash management features are basic.
- Cryptocurrency trading is limited.
- Advanced trading tools are lacking.
 Analysis by All-app
When money management has to happen between errands, appointments, and a crowded commute, an app’s design can make the difference between checking in and putting it off. Robinhood Banking is a finance app from Robinhood, and I find its streamlined presentation appealing for quick, routine check-ins. Its focus is everyday banking rather than a deep investing workstation, so it makes most sense for someone who wants a simple place to keep an eye on money without turning every visit into a research session.
Readable screens and straightforward navigation
The app’s restrained visual style can help keep the main task in view: checking a balance, reviewing activity, or getting a sense of spending. That kind of uncluttered layout is useful when I’m opening a finance app for a specific reason and don’t want to hunt through a maze of menus. The trade-off is that a minimal interface can leave less room for explanation. If a label or category is unfamiliar, a new user may need to pause and work out what it means rather than relying on a long on-screen guide.
I would approach the app as a quick dashboard, not as a replacement for understanding my finances. A notification can draw attention to a transaction, but it doesn’t explain whether the purchase fits a monthly plan or whether a recurring charge is still worthwhile. My practical habit would be to pair quick checks with a regular review: scan the activity during the week, then look over the pattern when I have enough time to make a decision. That keeps convenience from becoming a substitute for attention.
Motor and sensory needs in everyday use
Simple navigation can be helpful for people who prefer fewer steps and less visual clutter, but that alone does not tell me how well the app will work for every ability or device setup. Small touch targets, screen-reader labels, text scaling, contrast, and motion preferences all affect a banking app in ways that a clean appearance cannot show. I would test those basics on the phone I actually use before making this the place I rely on for time-sensitive money tasks.
There is also a sensory trade-off with transaction alerts. They can make activity easier to notice, especially when I’m trying to catch an unexpected charge, but frequent prompts may be distracting. I’d keep the alerts that help me act and adjust the rest through the phone’s notification controls if they become noisy. For someone who has difficulty using touchscreens, navigating menus, or reading compact financial information, a branch, a phone-based service, or a banking app already known to work with their assistive setup may be a better primary option.
Access across places and routines
The strongest use case is a short check while I’m away from a desk: confirming that a purchase appeared, reviewing recent activity after grocery shopping, or getting a quick view before deciding whether a planned expense can wait. A useful routine is to check the account after a spending-heavy day rather than repeatedly refreshing it. That gives each glance a purpose and makes the information easier to act on.
For context, the app is listed as free, with an Everyone age rating, and it has reached over 100,000 installs. Its average rating is 4.9 from around 15,000 ratings, which suggests a positive reception, though a rating can’t tell me whether a particular accessibility need or banking workflow will be handled well. It was released on March 19, 2024, and version 2.3.1 requires Android 7.0 or later. I’d still check that the app works on my device and fits my needs before moving important routines into it.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Getting Started with Robinhood Banking
The first thing you'll notice when you download Robinhood Banking is its minimalist design. The interface is super user-friendly, which is a relief because, let's face it, nobody wants a financial app that needs a manual to navigate. Signing up is a breeze, too. It took me less than five minutes to set up my account, and I was ready to explore its features.
Features That Shine
Now, let's talk about what you can do with this app. At its core, Robinhood Banking is all about simplifying your financial life. You can track your spending, set up budgets, and even get insights into your financial habits. It’s like having a personal financial advisor in your pocket.
One feature I found particularly handy is the instant notifications. Whenever you make a transaction, you get a notification right away. It's a small thing, but it really helps you stay on top of your spending. Plus, the budgeting tool is quite intuitive. You can set limits for different categories, and the app will alert you if you're getting close to overspending. Trust me, it’s a game changer for keeping those impulse buys in check.
Security You Can Trust
Of course, with any banking app, security is paramount. Robinhood Banking doesn’t skimp here. They have all the standard security protocols in place, like biometric login and encryption. I felt pretty secure using it, knowing my data was well-protected. They also offer two-factor authentication, which adds an extra layer of security.
Where It Falls Short
But hey, no app is perfect, right? One thing I noticed is that while the app is great for managing day-to-day finances, it lacks some advanced features. For instance, if you're looking for in-depth investment options or detailed analytics, you might find it a bit lacking. It's more of a starter kit for those new to personal finance management.
Also, customer support could use a bit of improvement. I had a minor issue with a transaction, and getting through to someone was a bit of a hassle. A more responsive support system would definitely enhance the user experience.
Choosing a role for it in your financial life
I would compare this with the finance apps people commonly use in two broad ways: a traditional bank’s app and a dedicated budgeting tool. A bank app is usually the natural choice when the main job is handling an existing account and its services. A budgeting app may suit someone who wants to analyze spending in more depth. Robinhood Banking sits closer to the simple daily check-in: its spending and budget tools are useful, but I wouldn’t choose it on the assumption that it will replace every banking relationship or provide detailed financial analysis.
That distinction matters if you’re deciding whether to move over. Before depending on any banking app, I’d check which accounts and services it supports for the tasks I actually perform, how I would handle a time-sensitive problem, and whether its tools give enough detail for my decisions. For a person who already has a preferred bank and wants a separate, uncomplicated way to monitor day-to-day habits, this app may be a useful fit. If having all financial products, service channels, and specialized reporting in one place is essential, I’d compare it carefully with a full-service bank or a purpose-built money-management app.
A practical routine, not another stream of alerts
Imagine I’m coming home from a grocery run and want to check that the purchase has appeared where I expect it. A transaction notification can make that quick; later, I can review the week’s spending and see whether groceries are approaching the limit I set. The useful move is to treat the alert as a prompt to verify, not as a complete budget review. If I’m already getting too many notifications, I’d prioritize the ones that help me spot activity and use a planned check-in for everything else.
There’s another small but worthwhile budgeting habit: make category limits reflect real decisions, not perfect behavior. If a limit is so tight that ordinary spending triggers constant warnings, I’m more likely to ignore the alerts. I’d start with categories where a nudge could change what I do, then adjust the limits after observing a normal stretch of spending. That makes the budgeting feature a practical cue rather than a source of guilt or noise.
I’d also keep a fallback route for anything urgent. A mobile app is convenient for routine checks, but a disputed or confusing transaction can require more than a notification and a budget screen. Since my experience with support involved some friction, I wouldn’t make the app my only plan for resolving a problem. Knowing how I would reach help, and keeping access to another banking option for essential payments, is sensible preparation rather than a reason to avoid using it.
Who is likely to appreciate it—and who may not
I can see it working best for someone who wants a low-friction way to monitor everyday spending, is comfortable managing money on a phone, and values straightforward budgeting over deep analysis. It can also suit a beginner who wants a visible nudge when a category is nearing its limit, provided they’re willing to review the numbers instead of treating the app as an adviser. Its everyday focus is a strength when the goal is awareness and habit-building.
I’d steer away if you need extensive investment research, detailed reporting, or a single app that replaces a more complete banking setup. I’d also be cautious if the interface is difficult to use with your assistive technology or if alerts create more stress than clarity. Those are personal fit questions, not flaws that a favorable average rating can settle. Testing a small, ordinary task first—such as locating recent activity and adjusting a budget—will tell you more than committing to a major financial change immediately.
Final Thoughts
So, is Robinhood Banking worth your time? If you're looking for a straightforward, easy-to-use app to keep an eye on your finances, I'd say give it a shot. It's perfect for those who want a no-fuss approach to managing their money. The app does a lot of things right and keeps things simple, which is a big win in the world of mobile banking.
While it may not replace a full-fledged banking service for everyone, it's certainly a step in the right direction for making banking accessible and manageable. Plus, the peace of mind you get from its security features is a sweet bonus.
In a nutshell, if you're ready to take control of your finances with just a few taps and swipes, Robinhood Banking might just be your new best friend. Give it a try and see how it fits into your financial routine.
Frequently Asked Questions
What is Robinhood Banking and how does it work?
Robinhood Banking is a feature within the Robinhood app that offers financial services, including a cash management account and a debit card. It allows users to earn interest on uninvested cash, make purchases, and manage their finances seamlessly. The service integrates with the Robinhood platform, providing a streamlined experience for investment and banking needs.
Is my money safe with Robinhood Banking?
Yes, Robinhood Banking ensures the safety of your funds by holding your cash in FDIC-insured partner banks, providing up to $1.25 million in FDIC insurance. Additionally, Robinhood uses advanced security measures, including encryption and two-factor authentication, to protect your personal and financial information.
Are there any fees associated with Robinhood Banking?
Robinhood Banking offers a fee-free structure with no account maintenance fees, no minimum balance requirements, and no charges for ATM withdrawals within the nationwide network. However, out-of-network ATM withdrawals may incur a fee, so it’s essential to check the terms for any potential costs.
How do I access my funds with Robinhood Banking?
You can access your funds through the Robinhood app, which provides a comprehensive view of your account balance, transaction history, and spending insights. Additionally, the Robinhood debit card can be used for purchases and ATM withdrawals, offering flexibility and convenience in managing your finances on the go.
What should I do if I encounter issues with Robinhood Banking?
If you experience any issues with Robinhood Banking, you can contact their customer support through the app or website. Robinhood provides a Help Center with detailed articles and a support team ready to assist with any questions or concerns, ensuring a smooth user experience.